NRI Investment in Indian Real Estate
19 July 2025|15 Minutes Read
By : Ganga Realty

The Ultimate Guide to NRI Investment in Indian Real Estate (2026)

India’s real estate market has emerged as one of the most attractive investment destinations for Non-Resident Indians (NRIs). Rapid infrastructure development, rising property values, favorable government reforms, increasing transparency through RERA, and growing demand for premium housing have made Indian real estate an excellent long-term wealth creation opportunity.

If you’re considering premium real estate opportunities, explore our collection of luxury apartments in Gurgaon that combine world-class amenities with excellent long-term investment potential.

This comprehensive guide explains everything NRIs need to know about buying property in India—from eligibility and FEMA regulations to taxation, financing, documentation, and selecting the right investment location.

Why NRIs Are Investing in Indian Real Estate

Indian real estate has consistently remained one of the preferred investment choices for NRIs across the world. Unlike volatile financial assets, property offers stability, long-term appreciation, rental income, and emotional value by maintaining a connection with one’s homeland.

Several factors are contributing to this growing interest:

  • Strong economic growth and urbanisation
  • World-class infrastructure development
  • Rising demand for premium residential projects
  • Better transparency through RERA regulations
  • Increasing rental demand in metropolitan cities
  • Improved digital property buying experience
  • Attractive exchange rate advantages for many overseas investors

For NRIs earning in stronger foreign currencies, investing in India often provides better purchasing power and long-term capital appreciation compared to several international markets.

Before investing, it’s helpful to understand the fundamentals of property selection, risk assessment, and market trends in our comprehensive real estate investment guide.

Why 2026 Is a Great Time for NRI Property Investment

India’s property market continues to witness healthy demand across residential, luxury, and commercial segments. Government investments in highways, metro connectivity, airports, industrial corridors, and smart cities are transforming major urban centres into attractive investment destinations.
India_skyline_financial_growth

Cities like Gurgaon, Bengaluru, Hyderabad, Pune, Chennai, and Noida continue to attract both domestic and international investors due to their employment opportunities, expanding infrastructure, and growing rental markets.

Premium residential developments, branded housing projects, and integrated townships have further enhanced buyer confidence.

If your investment horizon is five to ten years, the current market presents strong potential for wealth creation. Many NRIs prefer under-construction properties for their appreciation potential. Learn more in our guide on the Benefits of Investing in Under-Construction Projects.

Can NRIs Buy Property in India?

Yes. Under Indian regulations, Non-Resident Indians (NRIs) are allowed to purchase residential and commercial properties in India without requiring prior approval from the Reserve Bank of India (RBI), provided the transaction complies with FEMA regulations.

NRIs can purchase:

  • Apartments
  • Villas
  • Independent houses
  • Residential plots
  • Commercial offices
  • Retail shops
  • Commercial spaces

However, NRIs cannot generally purchase:

  • Agricultural land
  • Plantation property
  • Farmhouses
NRI_investor_meeting_real_estate

These restrictions are governed by FEMA regulations unless the property is acquired through inheritance or specific legal provisions.

NRIs looking to diversify their portfolio can also explore Commercial Property in Gurgaon, offering opportunities for rental income and business growth.

Steps for NRIs to Purchase Real Estate in India

If you’re an NRI planning to buy property in India, following a clear and well-structured process is crucial for a smooth and secure investment experience.

The journey involves several key steps, from setting your investment goals and arranging finances to conducting legal due diligence and ensuring regulatory compliance. Here’s a concise checklist to guide you through the essential steps for NRIs to purchase real estate in India:

Step 1: Define Your Investment Goal

Ask yourself:

  • Is this a long-term investment?
  • Will you live here after returning to India?
  • Are you looking for rental income?
  • Is capital appreciation your priority?
  • Are you investing for your family?

Your objective will determine the ideal city, budget, and property type. If you’re looking for budget-friendly investment opportunities, explore our Affordable Housing Projects in Gurgaon that combine affordability with future growth potential.

Step 2: Choose the Right City

Compare cities based on:

  • Employment opportunities
  • Infrastructure
  • Rental demand
  • Future appreciation
  • Connectivity
  • Builder reputation
  • Lifestyle

For premium residential investments, Gurgaon continues to be one of the strongest markets due to its corporate ecosystem, infrastructure, and luxury housing supply.

Step 3: Select a Trusted Developer

Always evaluate the developer’s:

  • Track record
  • Delivered projects
  • Construction quality
  • Customer reviews
  • Financial credibility
  • RERA compliance
  • Delivery timelines

Choosing a reputed developer significantly reduces investment risk.

Step 4: Verify Legal Documents

Before paying the booking amount, verify:

  • Title documents
  • Land ownership
  • Building approvals
  • RERA registration
  • Encumbrance certificate
  • Approved layout plans
  • Environmental approvals (where applicable)

Professional legal due diligence is highly recommended. Always verify whether a project is registered with HRERA before making any investment decision. Our HRERA verification guide explains the process step by step.

Step 5: Arrange Financing

Decide whether to:

  • Make full payment
  • Opt for a home loan
  • Use NRE/NRO funds
  • Finance through overseas savings

Compare loan terms before finalising.

Step 6: Book the Property

Once satisfied:

  • Pay the booking amount
  • Sign the booking form
  • Receive the allotment letter
  • Review the Builder-Buyer Agreement carefully before signing

Step 7: Register the Property

Property registration involves:

  • Payment of stamp duty
  • Registration charges
  • Execution of the sale deed
  • Updating ownership records

If you are overseas, registration can often be completed through a legally executed Power of Attorney.

Documentation Required for NRI Property Purchase

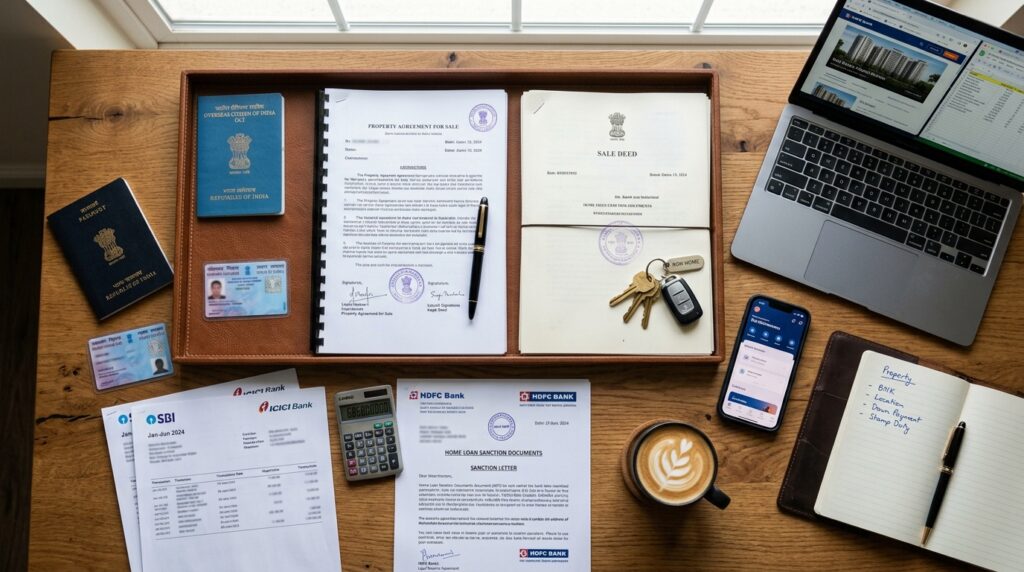
If you are an NRI planning to purchase property in India, it’s essential to have the correct set of documents ready to ensure a smooth transaction and legal compliance.
NRI_property_investment_document

Below is a checklist of the key documents typically required:

  • Valid Indian passport or OCI/PIO card
  • PAN card (Permanent Account Number)
  • Proof of NRI status
  • Recent photographs
  • Power of Attorney (if not present in India)
  • Overseas and Indian residential address proof
  • Relevant bank account details (NRE/NRO/FCNR)

Understanding the registration process and required documentation can help NRIs complete their property purchase smoothly. Our guide on documents required for property registration will help you with this.

Summary Table: Essential Documents for NRIs Buying Property in India

Document TypeExamples/Details
IdentificationPassport, OCI/PIO card, recent photo
Status ProofVisa/Work permit, PAN card
Address ProofUtility bill, bank statement, Aadhar card (optional)
Account DetailsNRE/NRO/FCNR bank account credentials
Legal AuthorizationSpecial Power of Attorney (if purchasing remotely)
Financial ProofPayslips, income tax returns (especially for loans)
Property DocumentsSale deed/title deed, approved plan, NOC, occupancy or completion certificate

Note: Always have original documents and attested copies handy, and work with a legal expert to verify the authenticity of property-related paperwork before completing the transaction.

Difference Between NRI, OCI and PIO

Many overseas Indians are confused about these categories.

CategoryCan Buy Residential PropertyCan Buy Commercial PropertyCan Buy Agricultural Land
NRIYesYesNo
OCIYesYesNo
PIO (existing cardholders)YesYesNo

OCI cardholders enjoy property purchase rights similar to NRIs for residential and commercial properties.

Benefits of Investing in Indian Real Estate

1. Long-Term Capital Appreciation

Indian metropolitan regions have consistently witnessed property appreciation driven by infrastructure development, employment generation, and urban expansion.

Premium micro-markets often deliver stronger long-term returns compared to saturated locations.

2. Attractive Rental Income

Cities with strong corporate presence generate healthy rental demand.

Luxury apartments, especially in business hubs, attract:

  • Corporate executives
  • Expats
  • Working professionals
  • Senior management
  • Global consultants

This creates a stable rental income opportunity for NRI investors.

3. Portfolio Diversification

Real estate helps diversify investments beyond equities, mutual funds, and fixed-income assets.

Owning physical assets in India also reduces dependency on a single investment class.

4. Emotional Security

Many NRIs eventually plan to return to India after retirement.

Purchasing a property today allows families to secure a future residence while benefiting from property appreciation during the ownership period.

5. Currency Advantage

When earnings are in USD, GBP, EUR, AED, SGD, or other stronger currencies, Indian real estate often becomes relatively more affordable due to exchange rate advantages.

This increases purchasing power and enables investment in premium developments.

RBI Guidelines for NRI Property Investment

The Reserve Bank of India permits NRIs to invest in residential and commercial properties without prior approval under FEMA regulations.
Property_agreement_with_legal_do

Payments for property purchases should generally be made through:

  • NRE Account
  • NRO Account
  • FCNR Account
  • Normal banking channels

Cash transactions should always be avoided. Maintaining complete banking records helps ensure transparency and simplifies future repatriation of funds.

FEMA Rules Every NRI Should Know

The Foreign Exchange Management Act (FEMA) regulates property transactions involving NRIs.

Important provisions include:

  • Residential property purchase is permitted.
  • Commercial property purchase is permitted.
  • Agricultural land cannot generally be purchased.
  • Plantation property is restricted.
  • Farmhouses cannot normally be purchased.
  • Sale proceeds may be repatriated subject to FEMA and RBI conditions.
  • Property can be inherited according to Indian succession laws.

Understanding FEMA before investing helps avoid unnecessary legal complications.

Essential Legal Checks Before Buying Property
Leather_folder_with_documents

Never invest without conducting proper due diligence. Before making any payment, verify the following:

  • Clear property title
  • RERA registration
  • Approved building plans
  • Occupancy or completion status
  • Encumbrance certificate
  • No outstanding legal disputes
  • Builder reputation
  • Bank approvals
  • Construction progress
  • Payment schedule

Professional legal verification is highly recommended, especially for high-value investments.

Why RERA Verification Is Important

The Real Estate (Regulation and Development) Act (RERA) has significantly improved transparency in India’s real estate sector.

Before investing, verify:

  • Project registration number
  • Developer details
  • Construction timeline
  • Approved plans
  • Litigation status
  • Quarterly project updates

Buying a RERA-registered property greatly reduces investment risks and enhances buyer confidence.

Home Loans for NRIs in India

One of the biggest advantages for NRIs investing in Indian real estate is the availability of home loans from leading Indian banks and housing finance companies. Many financial institutions offer dedicated NRI home loan products with competitive interest rates, flexible repayment options, and simplified documentation.
Financial_planning_workspace

Eligibility for NRI Home Loans

While eligibility criteria vary across lenders, most banks consider:

  • Age (typically 21–65 years)
  • Stable overseas employment or business income
  • Minimum work experience
  • Country of residence
  • Credit profile
  • Existing financial liabilities
  • Property value and location

Banks generally finance 75%–90% of the property’s value, depending on the loan amount and applicant profile.

Documents Required for an NRI Home Loan

Keep these documents ready:

Personal Documents

  • Passport
  • Valid Visa/Residence Permit
  • PAN Card
  • OCI Card (if applicable)
  • Overseas address proof
  • Passport-size photographs

Income Documents

  • Salary slips (last 3–6 months)
  • Employment contract
  • Bank statements
  • Income tax returns (if applicable)
  • Overseas credit history (where required)

Property Documents

  • Builder-Buyer Agreement
  • Allotment Letter
  • Approved Building Plans
  • RERA Registration Details
  • Sale Agreement
  • Cost Sheet

Applying with complete documentation can significantly reduce loan processing time.

Understanding Power of Attorney (PoA)

Many NRIs cannot travel to India for every stage of the purchase process. In such cases, a trusted family member or representative may act on their behalf through a legally executed Power of Attorney.

A PoA can be used for:

  • Property booking
  • Signing agreements
  • Loan documentation
  • Registration
  • Taking possession

For validity in India, the Power of Attorney should generally be:

  • Executed in the country of residence
  • Attested by the Indian Embassy or Consulate (where applicable)
  • Adjudicated or stamped in India as per state laws

Consult a legal expert to ensure compliance with local requirements.

Tax Implications and Benefits for NRI Investors
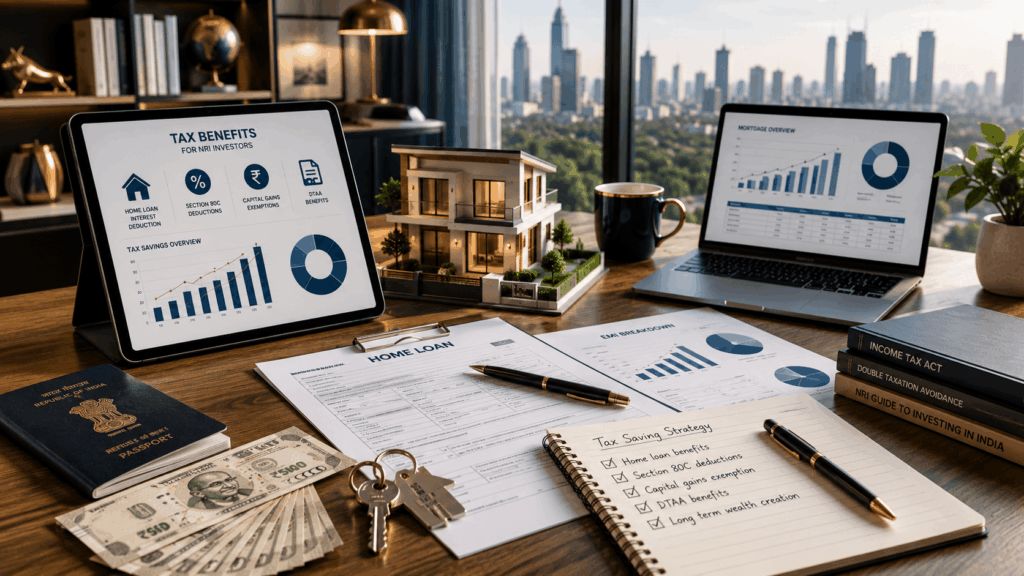
Modern workspace with tax planning tools

Taxation on Acquisition

  • NRIs must pay stamp duty, registration charges, and GST (if applicable).
  • No TDS on new property purchase but TDS applicable on sale to Resident Indian.

Income from Property

  • Rental Income: Taxed at applicable slab rates after standard deduction (currently 30%) for repairs and maintenance.
  • Tax Benefits: Home loan principal (Section 80C) and interest (Section 24) enjoy the same income tax benefits as resident Indians.

Capital Gains Tax

  • Short-term gain (holding <2 years): Taxed as per applicable slab.
  • Long-term gain (holding >2 years): Taxed at 20% with indexation benefits.

Repatriation of Funds

  • Capital and gains can be repatriated, subject to compliance with FEMA, up to USD 1 million per financial year after payment of applicable taxes.

Summary Table: Major Tax Highlights for NRI Real Estate Investors (2026)

CategoryTax Rate or BenefitKey Points
Rental IncomeSlab rate (30% TDS)30% standard deduction, claims allowed
Short-Term Capital GainsSlab rateProperty held <2 years
Long-Term Capital Gains20% (w/ indexation/forex benefit)Property held >2 years; potential 72% tax saving
Property Sale TDS20% (LTCG), 30% (STCG)Deducted by buyer at sale time
Section 80C Deductions₹1.5 lakh/yearIncludes home loan principal repayment, LIC, etc.
Section 24 (Interest)Up to ₹2 lakh/yearOn self-occupied property loans
Capital Gains ExemptionFull/partial under Section 54, 54EC, 115FOn reinvestment within permitted assets
DTAA ReliefAs per treatyTax credit or exemption in both countries
RepatriationUp to $1 million/yearSale/rental proceeds after taxes
TDS/TCS ThresholdsLRS: ₹10 lakh/yearHigher limit for outbound remittances

Also Read:- Why Luxury Apartments in Gurgaon for Sale Are Trending in 2026

Best Indian Cities for NRI Real Estate Investment

CityGrowth DriversProperty TypesNRI Appeal
GurgaonBusiness hub, infrastructureLuxury & high-end, apartmentsStrong price appreciation, cosmopolitan
BangaloreIT, startups, job magnetVillas, apartmentsHigh rental income, global connectivity
HyderabadPharma, IT, affordable luxuryIntegrated townshipsModern amenities, robust growth
PuneEducation, tech parks, manufacturingGated communities, villasSteady returns, best for family-settling
Delhi-NCREconomy, retail, connectivityPlots, luxury apartmentsDiverse options, international schools
ChennaiManufacturing, logisticsApartments, mid-incomeStable prices, expat-friendly

Hot Tip: Gurgaon, Bangalore, and Hyderabad remain top favorites due to rapid growth, cosmopolitan lifestyle, and investor-friendly policies.

Also Read:- Luxury Residences in Gurgaon vs Mumbai. Why Smart Investors Are Moving to Gurgaon City.

Why Gurgaon Is One of the Best Cities in India for NRI Property Investment

Among India’s leading real estate destinations, Gurgaon (Gurugram) has consistently attracted strong interest from Non-Resident Indians due to its thriving corporate ecosystem, premium residential developments, modern infrastructure, and long-term investment potential.
Gurgaon_aerial_photograph

The city has evolved into a global business hub, housing numerous Fortune 500 companies, multinational corporations, IT parks, and financial institutions. This steady employment growth continues to fuel demand for quality housing and supports both capital appreciation and rental income.

For NRIs seeking a balance between wealth creation and lifestyle, Gurgaon offers a compelling investment opportunity.

Before selecting a location, review the latest property rates in Gurgaon to compare micro-markets and understand current price trends.

Best Areas in Gurgaon for NRI Investment

Sector 84

Located close to Dwarka Expressway, Sector 84 has emerged as one of New Gurgaon’s fastest-growing luxury destinations. Advantages include:

  • Excellent connectivity
  • Premium residential developments
  • Future infrastructure
  • High appreciation potential
  • Growing social infrastructure

Sector 84 has become one of New Gurgaon’s most desirable luxury destinations, offering spacious residences and excellent connectivity. If you plan to buy luxury apartments in Sector 84, Gurgaon, you should check this.

Sector 85

Sector 85 has become one of the city’s most sought-after luxury residential locations. It offers:

  • Premium high-rise developments
  • Wide roads
  • Upcoming commercial hubs
  • Strong rental demand
  • Excellent connectivity

Sector 85 is emerging as a preferred destination for premium high-rise developments with excellent future growth prospects. If you think to buy luxury apartments in Sector 85, Gurgaon, you should check this.

Golf Course Road

Ideal for luxury homebuyers seeking established infrastructure, premium amenities, and strong rental demand.

Golf Course Extension Road

One of Gurgaon’s fastest-developing luxury corridors with increasing demand from professionals and investors.

New Gurgaon

New Gurgaon continues to attract investors due to:

  • Planned infrastructure
  • Wider roads
  • Better urban planning
  • Competitive pricing
  • Long-term appreciation potential

Sohna

Supported by the Delhi-Mumbai Expressway and ongoing infrastructure projects, Sohna has emerged as an attractive destination for both affordable and premium investments. Looking for emerging investment destinations? Explore our Sohna Real Estate Investment Guide to understand its infrastructure growth and future potential.

If you’re specifically looking at Gurgaon, read our detailed guide on why NRIs should invest in Gurgaon real estate to understand why the city remains one of India’s most attractive investment destinations.

Why NRIs Should Consider Ganga Realty’s Nandaka & Anantam

Ganga Realty is a standout developer in Gurgaon, offering premium, internationally-styled homes with future-ready amenities.

  • Prime Gurgaon address—both projects on the fast-appreciating Dwarka Expressway growth corridor
  • Unmatched luxury and amenities rarely found in the Indian market
  • Sustainability and future-readiness (AI-enabled homes, green certification)
  • High rental yield and strong resale value potential due to location and developer reputation
ProjectSectorHome TypesMajor HighlightsStarting Price
Nandaka843/4 BHK, PenthouseSky deck, 5 infinity pools, 1 lakh sq. ft. clubhouse, 80% greenery₹5.03 Cr*
Anantam853/4 BHKAI-enabled homes, tallest towers, 4 infinity pools, green certifications₹3.1 Cr*

Also Read:- GIFT City vs Gurgaon: Which Is the Better Investment Destination in 2026?

Why Luxury Real Estate Is Becoming the Preferred Choice for NRIs

The luxury housing segment has witnessed significant growth over the last few years.
Families_enjoying_luxury_amenities

Key reasons include:

  • Better construction quality
  • Premium amenities
  • Strong resale value
  • Higher rental demand
  • Professionally managed communities
  • Better security
  • Lifestyle-driven design

Luxury residences also tend to perform better during market cycles due to limited supply and strong demand from end-users. Explore some of the finest luxury residential projects in Gurgaon designed for modern lifestyles and long-term investment value.

Current Real Estate Trends for NRIs in India (2026)

The Indian real estate market continues to attract strong interest from NRIs in 2026, driven by robust infrastructure development, rising demand for luxury housing, and improved market transparency.

Investors are increasingly focusing on premium residential properties in high-growth cities such as Gurgaon, Bengaluru, Hyderabad, Pune, and Mumbai, where long-term capital appreciation and rental income opportunities remain strong.

Key trends shaping NRI investments include:

  • Growing demand for luxury homes with smart features and premium amenities.
  • Infrastructure-led growth around Dwarka Expressway, SPR, metro expansions, and other major corridors.
  • Preference for RERA-registered projects offered by trusted developers.
  • Digital property buying through virtual tours, online documentation, and remote transactions.
  • Rising interest in sustainable and smart homes with energy-efficient features.
  • Focus on long-term wealth creation through quality real estate investments rather than short-term gains.

These trends make 2026 an opportune time for NRIs to invest in India’s evolving real estate market, particularly in high-potential locations like Gurgaon.

Final Word: India’s Property Market Welcomes NRIs

Backed by policy support, digital advancements, and a mature regulatory ecosystem, the Indian property market is more NRI-friendly than ever. With careful planning, legal compliance, and targeting the right cities and developers, NRIs can gain not only handsome financial returns but also a sense of belonging and security.

At Ganga Realty, our vision is to create more than just homes—we build communities, foster legacies, and enable connections that stand the test of time and distance. As a leading luxury real estate developer in Gurgaon, we are dedicated to making your NRI investment journey secure, rewarding, and effortless.

Ganga Realty’s Nandaka and Anantam promise more than just luxurious homes—they offer peace of mind, smart investment potential, and a chance to be part of India’s urban future, all from a global vantage point

FAQs: NRI Property Investment in India

You will need your passport, PAN card, proof of NRI status, local and overseas address proof, and a PoA if you cannot be physically present.

Yes, the same tax deductions as resident Indians are available on home loan principal and interest paid.

  • Residential and commercial property: NRIs, PIOs, and OCIs can purchase residential (apartments, villas, plots) and commercial properties.

  • Restrictions: NRIs cannot directly purchase agricultural land, plantation property, or farmhouses. These can only be inherited or received as gifts, not bought outright.

  • Rental Income: Taxed as per Indian income tax slabs. A standard deduction is allowed for repairs.

  • Capital Gains Tax: Short-term (<2 years holding): taxed at slab rate. Long-term (>2 years): taxed at 20% with indexation.

  • GST: 5% on under-construction property purchases.

  • TDS: Buyers must deduct TDS (20% long-term, 30% short-term) when purchasing property from an NRI seller.

  • High returns: India’s real estate market is experiencing capital appreciation in metros and select urban corridors.

  • Rental demand: Strong rental yields in cities like Gurgaon, Bengaluru, Pune, and Hyderabad.

  • Transparency: Due to RERA and government reforms, the process is more secure and transparent than ever before.

  • Metros and Tier-1 cities (Gurgaon, Bengaluru, Mumbai, Hyderabad, Pune) are top choices for luxury, high-return, and Vastu-compliant homes.

  • Gated communities, smart homes, and integrated townships are especially popular because of security, amenities, and management support.
Enquire Now

Recent Posts

Smart Home Loan EMI Calculator
28 September 2026|17 Minutes Read

Smart Home Loan EMI Calculator

Buying a home is a major financial decision, and understanding your potential loan repayment is an important part of planning your purchase. A Home Loan EMI Calculator helps you estimate your monthly Equated Monthly Instalment (EMI) based on the loan amount, interest rate, and repayment tenure. Home Loan EMI Calculator Calculate your complete monthly EMI and year-wise repayment schedule. Loan Amount (₹) ₹1 Lakh ₹10 Crore Interest Rate (% p.a.) 1% 30% Loan Tenure (Years) 1 Year 40 Years Monthly EMI ₹0 Loan Amount ₹0 Total Interest ₹0 Total Payment ₹0 Total EMIs 0 Complete EMI Payment Breakdown MoM – Monthly Schedule YoY – Yearly Summary View Year: Download Monthly CSV Month EMI Principal Interest Total Paid Outstanding Balance Download Yearly CSV Year No. of EMIs Total EMI Paid Principal Paid Interest Paid Closing Balance Note: The calculator uses the standard reducing-balance EMI formula. Actual loan repayment schedules may vary depending on the lender, interest-rate changes, processing fees, prepayments and other applicable charges. Use the calculator above to estimate your monthly EMI, total interest, total repayment amount, principal and interest components, and complete home loan amortization schedule. You can also view the month-wise and year-wise repayment breakdown to understand how your loan balance changes throughout the tenure. Whether you are planning to purchase a home, understanding current property rates in Gurgaon, or comparing different financing options, calculating your potential EMI can help you plan your property budget. What Is a Home Loan EMI Calculator? A Home Loan EMI Calculator is an online financial tool that calculates the estimated monthly instalment payable on a home loan. To calculate your EMI, you generally need three inputs: Loan Amount: The amount you plan to borrow. Interest Rate: The applicable annual interest rate on the loan. Loan Tenure: The period over which you plan to repay the loan. Once these details are entered, the calculator estimates your monthly EMI and can also show the total interest payable and total repayment amount. A detailed amortization schedule can provide additional information, including how much of each EMI goes towards principal and interest and how much loan balance remains after every payment. Example Suppose you are considering a home loan of ₹50 lakh at an annual interest rate of 8.5% for 20 years. The calculator can estimate the monthly EMI and provide a complete repayment schedule covering all 240 monthly instalments. You can then change the loan amount, interest rate, or tenure to compare different scenarios. The calculator provides an estimate based on the information entered. Actual EMI and repayment terms may vary depending on the lender, applicable interest rate, fees, loan structure, and other conditions. What Is Home Loan EMI? EMI stands for Equated Monthly Instalment. It is the amount a borrower generally pays every month towards repayment of a loan. A typical home loan EMI consists of two primary components: Principal Component The principal component is the portion of your EMI that reduces the outstanding amount borrowed from the lender. Interest Component The interest component represents the cost charged by the lender for providing the loan. Under a typical reducing-balance repayment structure, the interest is calculated on the outstanding principal. As the principal reduces, the interest component generally decreases. Consequently, the composition of the EMI changes over the repayment period. In the initial period, a relatively larger portion of the EMI may go towards interest. As the outstanding balance reduces, the principal component generally becomes a larger portion of subsequent EMIs. How Is Home Loan EMI Calculated? Home loan EMI is generally calculated using a standard reducing-balance formula: EMI = P × r × (1 + r)ⁿ ÷ [(1 + r)ⁿ − 1] Where: P = Principal loan amount r = Monthly interest rate n = Total number of monthly instalments Converting Annual Interest Rate into Monthly Interest Rate If the annual interest rate is 8.5%, the monthly rate used in the formula is: 8.5 ÷ 12 ÷ 100 = 0.007083 Similarly, if the loan tenure is 20 years: 20 × 12 = 240 months The calculator uses these values to calculate the estimated EMI. What Factors Affect Home Loan EMI? Three major factors influence your estimated home loan EMI: Loan Amount: A higher loan amount generally results in a higher EMI when the interest rate and tenure remain unchanged. Interest Rate: A higher interest rate generally increases both the EMI and total interest payable. Loan Tenure: A longer tenure generally reduces the monthly EMI but can increase the total interest paid over the life of the loan. Therefore, comparing different combinations of loan amount, interest rate, and tenure can help you understand the potential financial impact of a home loan. How Does Home Loan EMI Calculation Help in Planning a Home Purchase? Calculating your potential EMI before purchasing a property can help you understand the financial commitment associated with a home loan. 1. Estimate Your Monthly Repayment An EMI calculation gives you an estimate of the monthly amount you may need to pay towards the loan. This can help you assess whether a particular loan amount fits within your planned budget. 2. Compare Different Loan Amounts You can use the calculator to compare different borrowing scenarios. For example: ₹30 lakh loan ₹40 lakh loan ₹50 lakh loan ₹60 lakh loan ₹75 lakh loan ₹1 crore loan Changing the loan amount allows you to see how the estimated EMI changes. 3. Compare Loan Tenures You can also compare different repayment periods such as: 10 years 15 years 20 years 25 years 30 years A shorter tenure generally results in a higher monthly EMI but can reduce the total period over which interest is charged. A longer tenure can reduce the monthly payment but may result in greater total interest over the loan period. 4. Understand the Total Cost of Borrowing The EMI is only one part of the overall picture. The calculator also shows: Total principal Total interest Total payment This helps you understand the estimated cost of borrowing over the entire loan tenure. 5. Plan Your Property Budget Before finalising a property, you can estimate different loan scenarios and understand how the potential EMI fits into your broader financial planning. However, the EMI should not be considered the only affordability factor. Buyers should also consider down payment requirements, registration and transaction costs, maintenance, insurance, taxes and other financial commitments. 6. Track Loan Repayment A detailed amortization schedule shows how your loan balance changes after each EMI. This provides a clearer view of your repayment progress over time. What Are the Key Features and Benefits of Home Loans? Home loans allow eligible borrowers to finance the purchase or construction of residential property, subject to lender-specific eligibility criteria and terms. Common features of home loans may include: Long Repayment Tenures Home loans can have relatively long repayment periods, depending on the lender and borrower eligibility. A longer tenure can reduce the monthly EMI, although it may increase the total interest paid. Monthly EMI Repayment Most standard home loans are repaid through regular instalments over the agreed tenure. Different Interest Rate Structures Lenders may offer different interest-rate structures, including floating-rate or other applicable arrangements. The applicable rate and terms depend on the lender and loan product. Part-Prepayment Options Some home loan products may allow borrowers to make additional principal payments, subject to applicable terms and charges. Reducing the outstanding principal can affect the future interest calculation. Balance Transfer Options Eligible borrowers may be able to transfer an existing home loan to another lender under applicable conditions. Borrowers should compare the overall cost, interest rate, fees and other terms before considering a balance transfer. Structured Repayment Schedule A home loan repayment schedule allows borrowers to understand the distribution of principal and interest over the loan tenure. The exact features, charges, eligibility requirements and conditions vary by lender. How to Use a Home Loan EMI Calculator? Using a Home Loan EMI Calculator is simple. Step 1: Enter the Loan Amount Enter the amount you are planning to borrow. For example, you can enter: ₹50,00,000 for a ₹50 lakh home loan. Step 2: Enter the Interest Rate Enter the applicable annual interest rate. For example: 8.5% per annum Step 3: Enter the Loan Tenure Enter the expected repayment period. For example: 20 years Step 4: Check Your Estimated EMI The calculator will automatically calculate your estimated monthly EMI. Step 5: Review Total Interest and Total Payment The calculator also shows the estimated: Total interest Total payment Principal amount Number of EMIs Step 6: Review the Amortization Schedule You can then view the complete monthly and yearly repayment schedule. This allows you to see exactly how the EMI is divided between principal and interest and how the outstanding balance reduces over time. Step 7: Compare Different Scenarios Change the loan amount, interest rate, and tenure to compare different borrowing scenarios. This can help you understand how different loan structures affect your estimated repayment. Once you have estimated your potential EMI, you can use our Carpet Area Calculator to understand the usable area of a property and explore floor-space calculations. Final Thoughts about Home Loan EMI Calculator A Home Loan EMI Calculator can be a useful starting point for understanding the potential financial commitment associated with buying a home. Instead of looking only at the monthly EMI, consider the complete repayment picture, including: Loan amount Interest rate Loan tenure Total interest Total repayment Principal repayment Outstanding balance The complete monthly EMI amortization schedule and year-wise repayment summary can provide additional insight into how your loan may be repaid over time. Before taking a home loan, compare applicable loan terms and consider your overall financial situation. The actual EMI and repayment schedule may vary depending on the lender's interest rate, fees, loan terms, rate changes and other applicable conditions. Use the calculator above to explore different home loan scenarios and understand how changing the loan amount, interest rate or tenure can affect your estimated repayment. If you are exploring premium residential projects in Gurgaon, you can also explore luxury apartments in Gurgaon and compare available homes based on location, configuration, size and overall property requirements. Explore Nandaka 84, Anantam 85, Ganga Valley and Kashi Residences to learn more about Ganga Realty's residential developments in New Gurgaon. Anantam 85 Ultra-luxury residences on Dwarka Expressway offering expansive green spaces and world-class amenities. Nandaka 84 Modern residential community in New Gurgaon designed for connectivity, comfort, and lifestyle. Ganga Kashi Residences Premium residential development offering peaceful living with contemporary amenities. Ganga Valley 78 Integrated township living with lush green spaces and a complete lifestyle ecosystem. FAQs About Home Loan EMI Calculator

Read More
East Facing House Vastu Plans for a Peaceful Life
17 September 2026|15 Minutes Read

East Facing House Vastu Plans for a Peaceful Life

📌 Quick Answer An east facing house is one of the most sought-after orientations in Vastu Shastra, associated with the rising sun, positive energy, and new beginnings. With the main entrance correctly placed, the kitchen in the southeast, and the master bedroom in the southwest, an east-facing home is believed to support health, prosperity, and mental peace. Introduction Stand at your main door, face outward as if stepping out, and check which direction you're looking. If it's east, you live in an east-facing house — and according to Vastu Shastra, you've inherited one of the most favourable orientations in Indian real estate. East-facing homes are consistently in demand across Delhi NCR, Gurgaon, Mumbai, and Bengaluru. The reason isn't just tradition — it's also practical. The east is the direction of the rising sun, and Vastu Shastra has associated it with health, clarity, and new beginnings for centuries. But an east-facing plot alone doesn't guarantee good Vastu. The placement of the main door, kitchen, bedrooms, and pooja room within that east-facing structure matters just as much as the orientation itself. This guide walks through the complete east facing house Vastu plan — from the basics to a room-by-room layout you can actually use. For broader guidance beyond orientation, see our Vastu tips for new homes — this guide focuses specifically on east-facing layouts. What Is an East Facing House? An east-facing house is one where the main entrance door faces east — not the road, not the largest window, and not the direction the plot itself runs. To confirm your home's facing: Stand inside your house at the main door, facing outward as though about to step out. Use a compass (or a phone compass app) rather than judging by the sun, since east and north are only 90 degrees apart and easy to misjudge. Confirm you're reading the main entrance, not a side door or balcony. Is an East Facing House Good According to Vastu? Yes — Vastu Shastra regards the east as one of the most auspicious directions for a home, second only to the northeast in overall favourability. Here's the reasoning Vastu Shastra gives: The east is ruled by Lord Indra, associated with authority, power, and good fortune. The rising sun in the east symbolises the removal of darkness and negativity, and is linked to health, vitality, and clarity of thought. An open, well-lit east side — both on the plot and inside the home — allows morning sunlight and positive energy to enter freely. The northeast corner (where north meets east) is the most sacred zone in the home, ideal for a pooja room or meditation space. Looking beyond east-facing properties specifically? Read our companion guide, How to Choose the Best Facing House as per Vastu, for a comparison across all major directions, or see our North Facing House Vastu guide if you're weighing both options. Common Myths About East-Facing Houses East-facing houses are often considered desirable in India, particularly because Vastu Shastra traditionally gives importance to the east direction. However, several popular beliefs about east-facing homes are oversimplified or misunderstood. The direction of the main entrance is only one factor; the actual layout, ventilation, natural light, room placement, site conditions and personal preferences also matter. MythReality"Every east-facing house is automatically lucky"The direction is favourable, but room placement, entrance position, and construction details still determine whether a home is truly Vastu-compliant."East-facing homes get too much heat"East-facing homes receive morning sun, which is gentle and warming — not the harsh afternoon sun that west-facing homes contend with."Only priests or spiritual families should choose east-facing homes"East-facing houses suit salaried professionals, business owners, and families alike — the Indra association relates to authority and success broadly."The whole east side of the plot must be left empty"What matters is that the east side stays lighter and more open than the south and west — a boundary wall or low landscaping is fine."An east-facing kitchen is ideal since it faces the sun"The kitchen should still be positioned in the southeast per Vastu, regardless of the house's overall facing."East facing is only about the entrance"Entrance direction sets the foundation, but room-wise placement — bedroom, kitchen, pooja room — is equally important for a Vastu-compliant home. An east-facing house can offer advantages such as the potential for pleasant morning light, but "east-facing" does not automatically mean perfect, nor does another orientation automatically mean unsuitable. The quality of a home ultimately depends on its design, planning, construction, surroundings and how well it meets the homeowner's requirements. Benefits of an East-Facing House East-facing houses are popular among many Indian homebuyers because the east direction receives the morning sun. Beyond traditional Vastu preferences, an east-facing home can also offer practical benefits when it is well planned and designed. 1. Health and Vitality Morning sunlight is rich in vitamin D and considered energising rather than harsh. Vastu practitioners associate consistent morning light with better sleep cycles, improved mood, and overall wellbeing for residents. 2. Positive Energy and New Beginnings The rising sun in the east is a universal symbol of fresh starts. Vastu Shastra holds that this energy, entering the home through a well-placed east entrance, supports clarity, motivation, and forward momentum for the household. 3. Career and Authority The east's association with Lord Indra — the king of the gods — is linked to leadership, authority, and professional recognition. Many buyers evaluating east-facing homes cite career growth as a key consideration. 4. Comfortable Natural Light Unlike west-facing homes, which absorb intense afternoon heat, east-facing homes receive their strongest light in the morning, when temperatures are cooler — a practical advantage in Gurgaon's hot summers. 5. Strong Resale and Rental Demand North and east-facing homes are consistently preferred by Vastu-conscious buyers in the NCR market. This demand asymmetry — Vastu-focused buyers will only shortlist certain facings, while others are indifferent — tends to support long-term resale value. East Facing House Vastu Tips — Room by Room For homeowners who follow Vastu Shastra, an east-facing house is often considered a favourable orientation because the east is associated traditionally with the rising sun. However, Vastu guidelines can vary across traditions and practitioners, so they are best treated as traditional planning preferences rather than scientifically established rules. Here is a practical room-by-room guide: Main Entrance The main entrance is the single most important Vastu element in an east-facing home. As with any direction, the east wall is conceptually divided into eight to nine energy zones (Pada), and not every position is equally favourable. Practical guidance for the entrance: The most auspicious entrance positions fall in the northern half of the east wall, closer to the northeast corner. Avoid placing the entrance in the extreme south of the east wall, closer to the southeast corner. Keep the entrance well-lit, clean, and free of clutter or shoes. A wooden main door, opening inward, is preferred over metal. Auspicious symbols (Om, Swastika) at the threshold are considered beneficial. Living Room Place the living room in the north, east, or northeast zone — this positions your primary social space directly in the home's energy-receiving area. Keep heavier furniture along the south and west walls. Leave the northeast corner of the living room open and uncluttered. Light, warm colours — white, cream, light yellow — work well with an east-facing home's natural light. Master Bedroom The master bedroom belongs in the southwest, regardless of the home's overall facing — this holds true for east-facing homes as it does for any other orientation. Sleep with your head pointing south or east. Avoid placing the master bedroom in the northeast, which is considered too energetically active for restful sleep. Guest bedrooms and children's rooms work well in the northwest. Kitchen The southeast corner — governed by Agni, the fire element — is the ideal kitchen location in an east-facing home. The cook should face east while cooking, meaning the stove should be positioned on the east wall of the kitchen. Never place the kitchen in the northeast — this is considered a serious Vastu defect in any home. Keep the stove (fire) and sink (water) on separate walls. Pooja Room The northeast corner is the most sacred zone in any home, and it's naturally energised in an east-facing house. Idols should face west (so the worshipper faces east) — a particularly strong alignment in an east-facing home. Avoid placing the pooja room under a staircase or adjacent to a bathroom. Keep the space bright, ventilated, and minimal. Bathroom and Toilet Bathrooms should be positioned in the northwest or west. Never place a toilet in the northeast — this remains one of the most significant Vastu defects regardless of house facing. Common bathrooms work well in the northwest zone. Staircase The staircase is best placed in the south, southwest, or west, rising from north to south or east to west. Avoid the northeast and the centre of the home (Brahmasthan) for staircase placement. The space beneath the stairs is suited to storage, not a kitchen, bedroom, or pooja room. Study or Home Office The east or northeast is well-suited to a study or home office in an east-facing house — the room's placement mirrors the home's overall orientation. Face east or north while working or studying for best results. Ensure the desk has natural light from an east-facing window. Balcony and Open Spaces Balconies, gardens, and open spaces belong on the east or north side. Keep the east side of the plot lighter and lower than the south and west. Avoid tall trees or heavy structures on the east side that could block morning sunlight. East Facing House Vastu Plan — Example Layouts Plot dimensions vary, but the underlying Vastu logic — heavier zones in the south/west, open zones in the north/east — stays consistent. Here's how it typically translates across common Indian plot sizes: Plot SizeApprox. AreaLayout Approach30x40 ft~1,200 sq. ft.The most common east-facing layout for a 2 BHK or compact 3 BHK. Entrance in the north half of the east wall; kitchen southeast; master bedroom southwest; pooja room northeast.30x60 ft~1,800 sq. ft.The extra depth allows a front garden on the east side, a larger living room in the north, and additional storage in the southwest.40x60 ft~2,400 sq. ft.Suited to a duplex layout — ground floor for living, kitchen, and a guest bedroom; first floor for the master bedroom (southwest) and children's rooms (northwest). As with any Vastu plan, the exact layout should be adapted to your specific plot, local building regulations, and structural requirements — treat this as a starting framework rather than a fixed blueprint. Before finalising a plot size, check your property's exact usable space with our carpet area calculator — it's a useful companion when mapping any of the layouts above onto a real plot." East Facing House Vastu — Dos and Don'ts ElementDoDon'tVastu ImpactMain EntrancePlace it in the northern half of the east wall.Avoid the extreme southeast corner.Affects the flow of positive energy and opportunity into the home.East Side of PlotKeep it open, light, and clutter-free.Avoid heavy structures or tall trees blocking morning sun.Preserves the energising quality of morning sunlight.Master BedroomPlace it in the southwest.Avoid the northeast.Southwest supports stability and restful sleep.KitchenPosition it in the southeast, cook facing east.Avoid the northeast.Keeps the fire element in its correct zone.Pooja RoomPlace it in the northeast, idols facing west.Avoid under staircases or next to bathrooms.The northeast is the most sacred zone in the home.StaircaseBuild in the south, southwest, or west.Avoid the northeast and the home's centre.Prevents obstruction of the home's core energy zone.Living RoomKeep it in the north or northeast.Avoid clutter and dark interiors.Encourages positivity and natural light. Common Vastu Mistakes in East-Facing Houses An east-facing house is often preferred by homebuyers who follow Vastu Shastra. However, simply choosing an east-facing property does not automatically mean the entire home follows Vastu principles. The entrance, room placement, proportions, openings and overall layout are also considered important in traditional Vastu planning. Here are some commonly discussed Vastu mistakes in east-facing houses: Entrance Too Close to the Southeast: Placing the main door too far south along the east wall shifts it away from the auspicious zone and closer to the fire-associated southeast — a common and avoidable error. Kitchen in the Northeast: As with any home, placing the kitchen in the northeast is one of the most frequent and serious Vastu mistakes — it introduces the fire element into the home's most sacred zone. Blocked East Side: Tall boundary walls, dense trees, or permanently parked vehicles on the east side block the very morning sunlight that makes east-facing homes desirable in the first place. Master Bedroom in the Northeast:Regardless of the home's facing, placing the master bedroom in the northeast is considered too energetically active for good sleep — the southwest remains the correct position. Cluttered Entrance: Even a well-positioned east-facing entrance loses much of its benefit if it's cluttered with shoes, dustbins, or dim lighting. East Facing House Vastu Remedies If structural changes aren't possible, Vastu offers practical fixes for existing issues: IssueRemedyEntrance in the Southeast ZonePlace a Vastu pyramid or Swastika symbol above the door; keep the area well-lit and welcoming.Kitchen in the NortheastUse a copper plate or Vastu pyramid beneath the stove; repaint the kitchen in warm, earthy tones.Master Bedroom in the NortheastUse grounding colours such as deep blue or teal; sleep with your head facing south.Blocked East SideKeep the area as clutter-free as possible; add lighting or a small water feature to restore energy flow.Toilet in the NortheastKeep it clean and dry, door closed, with a bowl of sea salt replaced weekly. Why Homebuyers Prefer East-Facing Properties For homeowners who follow Vastu Shastra, certain remedies are traditionally suggested when an east-facing house is believed to have a layout-related Vastu concern. These remedies are generally intended to improve the perceived balance of spaces without requiring major structural changes. It is useful to distinguish traditional Vastu practices from scientifically established effects: there is no scientific evidence that Vastu remedies directly cause changes in health, wealth or fortune. They can instead be viewed as cultural or personal practices. The demand for east-facing homes isn't purely traditional — it has measurable, practical drivers: Market demand: In cities like Gurgaon, Noida, and Mumbai, east and north-facing flats consistently draw higher enquiries, particularly among Vastu-conscious buyers who actively filter listings by facing. Practical comfort: Morning sunlight keeps interiors naturally lit through the day without the intense afternoon heat that west-facing homes absorb — a meaningful advantage during Gurgaon's summer months. Resale strength: Vastu-compliant orientations tend to hold their resale appeal better, since Vastu-focused buyers will only shortlist certain facings while others remain indifferent. Orientation is one of several key decisions when buying a home that homebuyers in Gurgaon weigh alongside location, budget, and builder reputation." As a leading real estate developer in Gurgaon, Ganga Realty factors these orientation preferences into its residential planning across its portfolio. Buyers exploring options in New Gurgaon can consider Nandaka in Sector 84, a modern residential community designed for connectivity and lifestyle; Anantam 85, an ultra-luxury high-rise development on Dwarka Expressway; Ganga Valley in Sector 78, an integrated township with extensive green spaces; and Ganga Kashi Residences in Sector 89, offering premium residences in a peaceful setting. Conclusion An east-facing house brings together tradition and practicality in a way few other orientations do — the symbolism of the rising sun, paired with genuinely comfortable morning light and strong resale demand. But orientation is only the starting point. The placement of the entrance within the east wall, the kitchen in the southeast, the master bedroom in the southwest, and a clutter-free approach to the home's most important zones all determine whether an east-facing house truly delivers a peaceful, prosperous living environment. As a leading real estate developer in Gurgaon, Ganga Realty designs its residential communities with these considerations in mind — so homebuyers don't have to choose between modern luxury and Vastu-aligned living. Looking for a Vastu-compliant home in Gurugram? Explore Ganga Realty's premium residential projects to find a home that balances comfort, positive energy, and long-term value. Anantam 85 Ultra-luxury residences on Dwarka Expressway offering expansive green spaces and world-class amenities. Nandaka 84 Modern residential community in New Gurgaon designed for connectivity, comfort, and lifestyle. Ganga Kashi Residences Premium residential development offering peaceful living with contemporary amenities. Ganga Valley 78 Integrated township living with lush green spaces and a complete lifestyle ecosystem.

Read More

Luxury Living In Gurugram

Discover thoughtfully designed residences that blend modern architecture,
premium amenities, and sustainable living in the heart of the city.

--> -->